Start here
The research question behind this note.
Ask an NRI investor if their portfolio is diversified, and most will say yes — after all, they hold half a dozen mutual funds, a couple of stocks, maybe some gold, and a fixed deposit or two. It looks diversified on a statement. It often isn’t,…
Ask an NRI investor if their portfolio is diversified, and most will say yes — after all, they hold half a dozen mutual funds, a couple of stocks, maybe some gold, and a fixed deposit or two. It looks diversified on a statement. It often isn’t, once you look at what’s actually driving those holdings up and down.
Diversification isn’t about how many things you own. It’s about how differently they behave from each other. Get that distinction wrong, and you can hold ten different funds that all fall together on the same bad day.
Key Takeaways
- Diversification is measured by correlation between holdings, not by the number of holdings you own.
- NRIs are prone to home bias in two directions at once: toward India (comfort investing “back home”) and toward their country of residence (comfort with what’s familiar there).
- A portfolio can be spread across many funds and still be effectively one big bet, if those funds are highly correlated with each other.
- Currency exposure is a commonly missed dimension of diversification — a portfolio can be asset-diversified but currency-concentrated.
- Real diversification for an NRI usually means spreading across asset classes, geographies, and currencies together, not just fund names.
This article explains general diversification concepts. It is educational information only, not investment advice or a recommendation for any specific asset allocation.
What Diversification Actually Means
Diversification works because different assets don’t all react the same way to the same event. When one zigs, another zags, or at least doesn’t zig as hard — and that offsetting behavior is what smooths out a portfolio’s overall ride. The technical term for this offsetting behavior is correlation, and it’s the entire point of diversifying. Owning more things only helps if those things are not all reacting to the market the same way.
The Classic NRI Trap: Home Bias in Two Directions
Most discussions of home bias focus on one direction: NRIs over-investing in India out of comfort, sentiment, or a belief that “I understand India better than anywhere else.” That’s real, and common. But NRIs are just as prone to a second, less-discussed version: over-investing in the comfort and familiarity of their country of residence — the local index fund, the local real estate, the local employer’s stock plan — simply because it’s what’s visible and easy to access day to day. Both are forms of the same underlying mistake: letting familiarity, rather than genuine diversification, drive where the money goes.
Correlation Is the Real Enemy, Not Number of Holdings
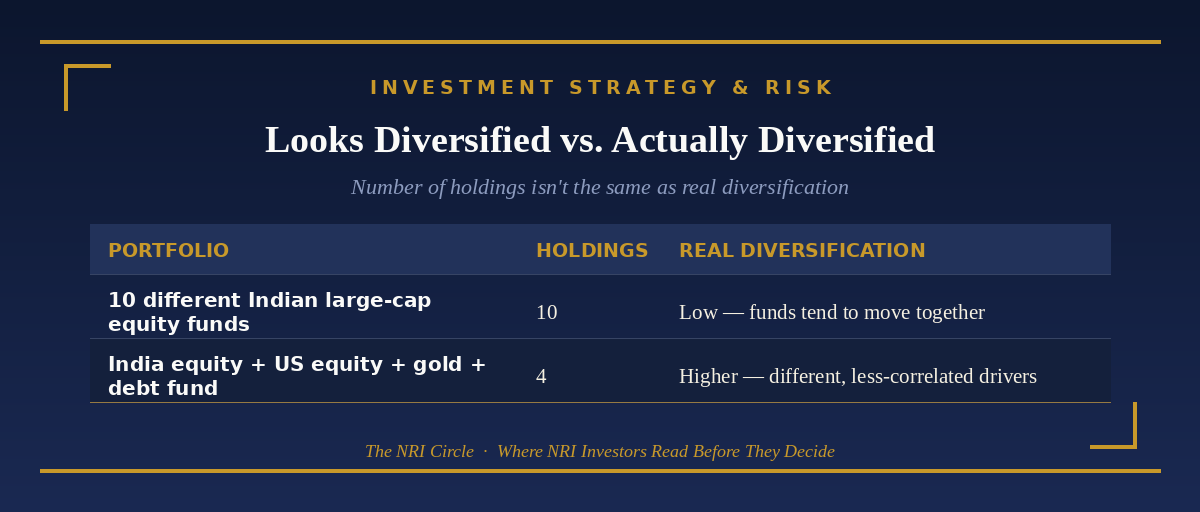
Here’s the trap in practice: an NRI holds ten different Indian large-cap equity mutual funds from ten different fund houses, and feels well diversified because of the number ten. But large-cap equity funds investing in the same broad Indian market tend to move together — they’re heavily influenced by the same handful of macro factors (India’s growth outlook, RBI policy, FII flows). In terms of actual diversification benefit, ten highly correlated large-cap funds behave much more like one large holding than ten independent ones.
Looks Diversified vs. Actually Diversified
Curious how this applies to your situation? Ask us — it's free →
The Currency Blind Spot
Continue reading
Get the complete cross-border research note.
Unlock the remaining analysis, risk considerations and official-source references. Enter your name and email for immediate access. WhatsApp and country are optional; newsletter consent is separate and optional.
Official sources and the full research note are available after access is granted.